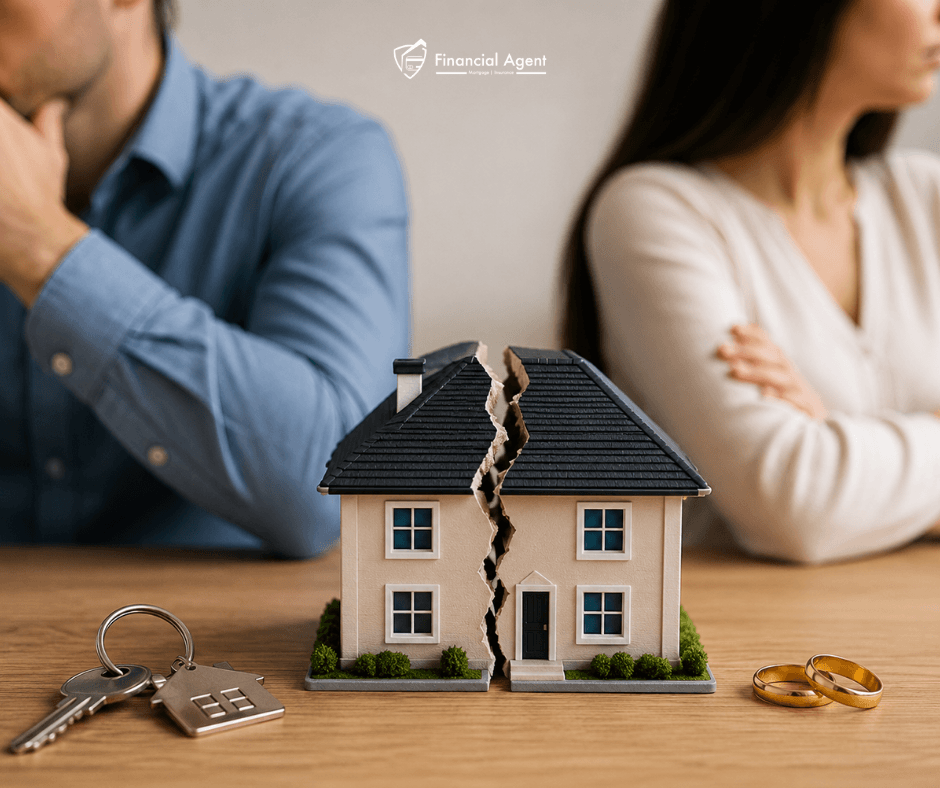
Divorce does not only mean the legal end of a marriage. When a couple owns property, has a mortgage, savings or other joint financial commitments, an important question arises: what happens to these after separation?
One of the most common misconceptions is that all assets are automatically divided 50/50 in a divorce. Another is that if the property was purchased before the marriage, or one spouse contributed a larger deposit, the home will automatically belong to that person.
In reality, dealing with financial matters following a divorce in England and Wales can be more complex.
Are Assets Always Divided 50/50 in a Divorce?
No. A 50/50 division may be a starting point, but it is not a formula automatically applied to every family.
If the spouses cannot reach an agreement and the financial matters are decided through the court, a range of factors may be considered, including the financial resources and needs of both parties, the length of the marriage, the standard of living, each person’s contribution to the family and other relevant circumstances.
The needs of any children are also an important consideration.
Therefore, the final outcome depends on the individual circumstances of each family.
What if the Property Was Purchased Before the Marriage?
The fact that a property was purchased by one spouse before the marriage does not necessarily mean that it will automatically remain entirely theirs following divorce.
For example, it may be relevant whether the property became the family home and what the financial needs of both spouses and any children are following separation.
In some circumstances, assets acquired before marriage may be treated separately, but there is no universal rule that applies to every case.
Therefore, the statement “I bought the house before we got married, so it will automatically remain mine after divorce” can oversimplify the situation.
If One Spouse Paid a Larger Deposit, Do They Automatically Receive a Larger Share?
Not necessarily.
The size of the original deposit and each spouse’s contribution towards mortgage payments may be considered, but they do not automatically determine how the property will be divided.
For a married couple, the financial circumstances are generally considered as a whole.
Direct financial contributions are not the only relevant factor. Other contributions to family life may also be taken into account, including situations where one spouse has primarily looked after the home or children.
What Happens to a Joint Mortgage After Divorce?
It is important to distinguish between the agreement between the former spouses and their obligations to the mortgage lender.
Divorce does not automatically remove one spouse from a joint mortgage.
Even if it is agreed that one person will keep the property, the mortgage itself must be dealt with separately.
For example, one spouse may want to keep the property and have the mortgage transferred into their sole name. However, an agreement between the couple alone is not enough.
The lender must agree to the change, and the person who wants to take over the mortgage must meet the lender’s criteria.
Can One Spouse Keep the House and Pay the Other Their Share?
Yes, this can be one possible option.
For example, the person who wants to keep the property may consider refinancing, potentially borrowing enough to pay the former partner the amount they are entitled to.
However, this is where mortgage affordability becomes important.
Even if someone has comfortably managed the monthly payments on a joint mortgage, this does not automatically mean that a lender will agree to provide the required mortgage amount in their sole name.
The lender will assess income, expenditure, existing financial commitments and its own lending criteria.
For this reason, during a divorce, the legal position and the practical mortgage options should be considered separately but alongside one another.
What if You Can Afford the Monthly Payment but Do Not Yet Qualify for the Mortgage on Your Own?
This situation is also possible.
For example, one former spouse may continue living in the property and making the mortgage payments but may not currently meet the lender’s criteria to have the entire mortgage transferred into their sole name.
As a result, the former partner may temporarily remain on the mortgage even if they no longer live in the property.
However, this still has financial consequences.
As long as someone remains named on the mortgage, their obligations to the lender continue. If problems arise with the payments, both borrowers may be affected, including their credit history and their ability to obtain finance in the future.
What if the Couple Was Not Married?
This is an important distinction.
The rights of people who live together without being married can differ from those of married couples or civil partners. In England and Wales, simply living together for a long period does not automatically create a legal “common law marriage.”
If a couple is married, the family home may be considered when financial matters are dealt with, even if the property is registered only in one spouse’s name.
For an unmarried couple, the position can be different. If the property legally belongs to only one partner, the other person may need to establish that they have a beneficial interest in the property.
Therefore, from a legal perspective, living together for many years is not the same as being married.
The Divorce Is Final. Does That Mean the Financial Relationship Is Over?
Not necessarily.
This is one of the most important points to understand.
Divorce ends the marriage, but financial matters need to be dealt with separately.
If former spouses reach an agreement regarding money, property and other assets, the agreement can be formally documented so that it becomes legally binding. If an agreement cannot be reached, the financial matters may need to be determined through the court.
Therefore, finalising a divorce should not be confused with bringing all financial ties between former spouses to an end.
What Should You Consider if You Have a Mortgage?
If you are going through a divorce and own a property together, it is important to consider the situation from two perspectives.
A Family Law specialist can explain each person’s rights, the available options for dividing assets and how a financial agreement can be legally formalised.
A mortgage adviser can assess the financing side of the situation: whether the mortgage could potentially be transferred into one person’s name, how much may be available based on income and existing financial commitments, and whether refinancing could be an option.
A solution that is possible from a legal perspective does not automatically mean that it will meet a mortgage lender’s requirements.
Important: This article provides general information and relates to England and Wales. Different rules apply in Scotland and Northern Ireland. Every family and financial situation is different, and legal matters should be discussed with a qualified Family Law professional.
Going Through a Divorce and Need to Review Your Mortgage Options?
We can help you assess the mortgage side of your situation, including whether the mortgage could be transferred into one person’s name, what refinancing options may be available and how much you may be able to borrow based on your income and financial commitments.
Book a ConsultationYour Home (or property) may be repossessed if you do not keep up repayments on your mortgage or any other debts secured on it.
This post is for information purposes only and does not constitute financial or mortgage advice.